Market overview and structural significance of the Oil Free Air Compressor Market
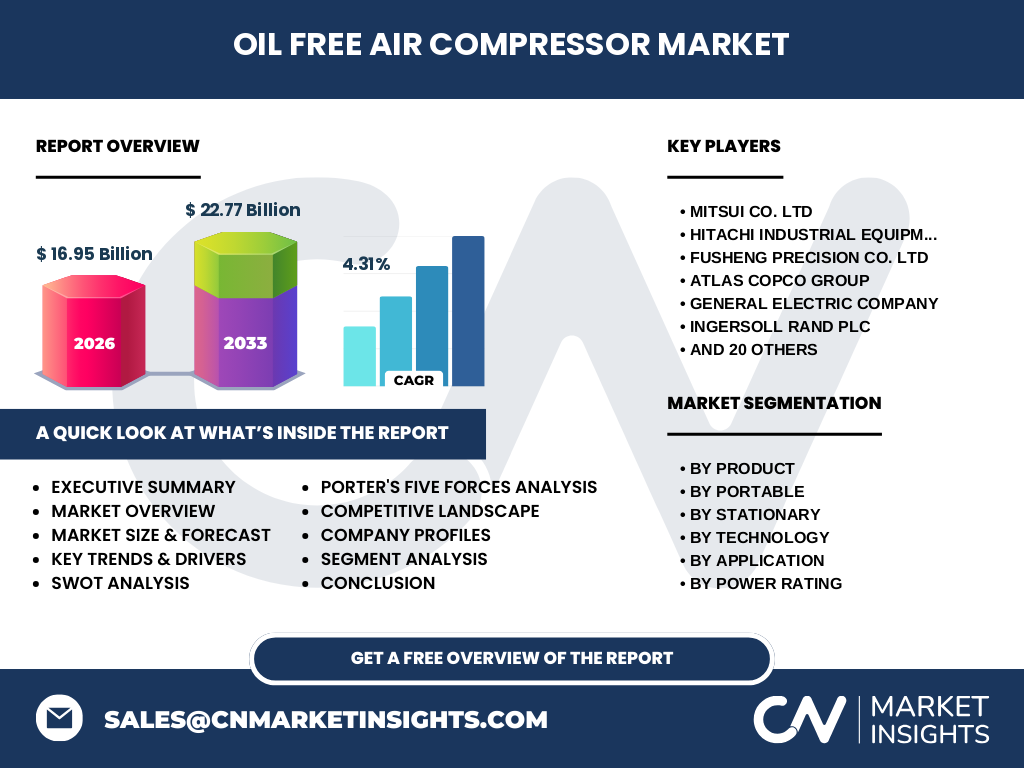
Our analysis indicates that the Oil Free Air Compressor Market represents a critical industrial sector valued at 16.95 Billion in 2026. This market encompasses precision-engineered systems delivering contaminant-free pneumatic power, essential for maintaining strict ISO 8573-1 Class 0 purity standards across sensitive manufacturing environments where oil vapor contamination risks catastrophic batch spoilage.
What are the core market drivers, restraints, challenges, and opportunities shaping the Oil Free Air Compressor Market?
The market is propelled by stringent FDA and ISO purity mandates, yet constrained by high initial capital expenditures for advanced rotary screw and centrifugal units. Supply chain bottlenecks involving high-grade specialty raw materials like titanium rotor coatings present ongoing challenges, while opportunities abound in energy-efficient upgrades for legacy factory floors.
Emerging trends and growth patterns in the Oil Free Air Compressor Market
Industry trends highlight a rapid migration toward variable speed drive (VSD) technology and IoT-enabled predictive maintenance. Manufacturers increasingly demand oil-free scroll and centrifugal compressors to reduce carbon footprints, aligning with stricter environmental compliance enforced by agencies like the EPA and European Union industrial directives.
How did the COVID-19 pandemic impact the Oil Free Air Compressor Market and shape its recovery trajectory?
The pandemic caused severe supply chain disruptions and temporary halts in automotive and chemical plant expansions. However, accelerated demand for pharmaceutical manufacturing capacity and medical-grade breathing air compressors fueled a resilient post-pandemic recovery, driving robust investments in automated, contactless compressed air infrastructure.
Competitive Benchmarking: Major players, concentration, and strategic dynamics
The market features moderate concentration, dominated by global innovators such as Atlas Copco Group, Ingersoll Rand plc, and Hitachi Industrial Equipment Systems Co. Ltd. These leaders maintain competitive moats through proprietary rotor coating technologies, extensive global distribution networks, and strategic acquisitions of specialized regional engineering firms.
Executive summary of key findings in the Oil Free Air Compressor Market
Our comprehensive research projects the global Oil Free Air Compressor Market size to expand from 16.95 Billion in 2026 to 22.77 Billion by 2033, achieving a steady 4.31% CAGR. Growth is anchored by uncompromising industrial quality demands in semiconductor fabrication and pharmaceutical processing.
Market forecast trajectory from 2027 to 2033
Based on our econometric modeling, the Oil Free Air Compressor Market industry trends point toward sustained expansion, scaling to 22.77 Billion by 2033. This trajectory reflects a healthy 4.31% CAGR from 2027, driven by massive capital outlays in greenfield electronics manufacturing plants and stringent food safety regulations.
Segmentation analysis across product, technology, application, and power rating
The market segments by product into stationary and portable units. Technologies include reciprocating, rotary screw, and centrifugal. Applications span food and beverage, pharmaceuticals, and semiconductors, while power ratings range from below 15kW to above 160 kW. Rotary and centrifugal units dominate high-capacity industrial nodes due to continuous duty cycle requirements.
Geographic distribution and regional performance across global territories
Regional performance varies significantly, with Asia-Pacific leading in volume due to rapid semiconductor fab and chemical processing expansions in South Korea and Taiwan. North America and Europe prioritize energy efficiency upgrades and strict adherence to ASME and ISO compressed air purity certifications.
In-depth regional review of key manufacturing hubs
Asia-Pacific acts as the primary growth engine, fueled by massive electronics manufacturing clusters utilizing heavy-duty centrifugal compressors. Meanwhile, European markets exhibit high demand for energy-optimized scroll stationary air compressors driven by stringent energy efficiency directives and carbon reduction goals mandated by regional regulatory bodies.
Strategic positioning of leading companies in the sector
Market participants deploy distinct growth plays. Atlas Copco Group and Ingersoll Rand plc focus on high-efficiency rotary and centrifugal architectures. Specialized players like Tamturbo Oyj and FS Elliott Co. LLC capture niche demand by emphasizing totally oil-free, water-injected, and high-purity turbo compressor technologies for electronics.
Porter's Five Forces analysis of competitive pressures
Bargaining power of buyers is moderate to high due to numerous established compressor brands, while supplier power remains tempered by specialized metallurgical requirements for corrosion-resistant rotors. Threat of substitutes is low given strict ISO Class 0 oil contamination legal thresholds in sensitive processing industries.
SWOT analysis of the Oil Free Air Compressor Market
Strengths include guaranteed contamination-free air and low maintenance rotary designs. Weaknesses involve high initial purchase costs. Opportunities stem from emerging green hydrogen production facilities requiring ultra-pure compression. Threats encompass raw material price volatility for high-grade stainless steel and specialized alloy components.
Value chain analysis from raw materials to end-users
The value chain starts with specialty alloy and rare earth mineral sourcing for motor magnets and rotors, moving through precision casting, assembly by OEMs like Sullair LLC or ELGI Equipments Ltd, and distribution via specialized engineering channels to end-users in chemical, semiconductor, and medical sectors.
Investment insights and strategic recommendations for stakeholders
Investors should target developers of variable-speed centrifugal and oil-free scroll compressors designed for sub-15kW to 55kW ranges. Capital allocation toward IoT-enabled predictive maintenance platforms offers high potential to capture recurring service revenue streams in high-uptime semiconductor and pharmaceutical manufacturing environments.
Conclusion and primary takeaways from the market analysis
The Oil Free Air Compressor Market analysis confirms a robust 4.31% CAGR leading to 22.77 Billion by 2033. Strict regulatory frameworks regarding air purity and surging demand from high-tech electronics manufacturing cement oil-free compression as a non-negotiable industrial utility for modern operations.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining global trade registry export data, primary stakeholder interviews with chief engineers across major chemical and semiconductor facilities, and secondary macroeconomic indicators from industrial manufacturing indices and national energy boards.
Scope of the report, coverage parameters, and analytical limitations
This report covers global market sizing from 2026 to 2033, evaluating stationary and portable product categories, power ratings from sub-15kW to above 160 kW, and key end-use verticals. Limitations include unforeseen geopolitical trade restrictions affecting raw material imports and localized currency fluctuation impacts.
Recent developments, corporate announcements, and strategic industry moves
Recent market dynamism includes strategic product launches focusing on heat recovery integration and ultra-low noise scroll compressors. Industry leaders like Kaeser Kompressoren SE and Gardner Denver have expanded manufacturing footprints in Southeast Asia to capture localized electronics supply chain relocations.